The lease or easement document
With the rent, the escalator, the renewal options and the current term end date.
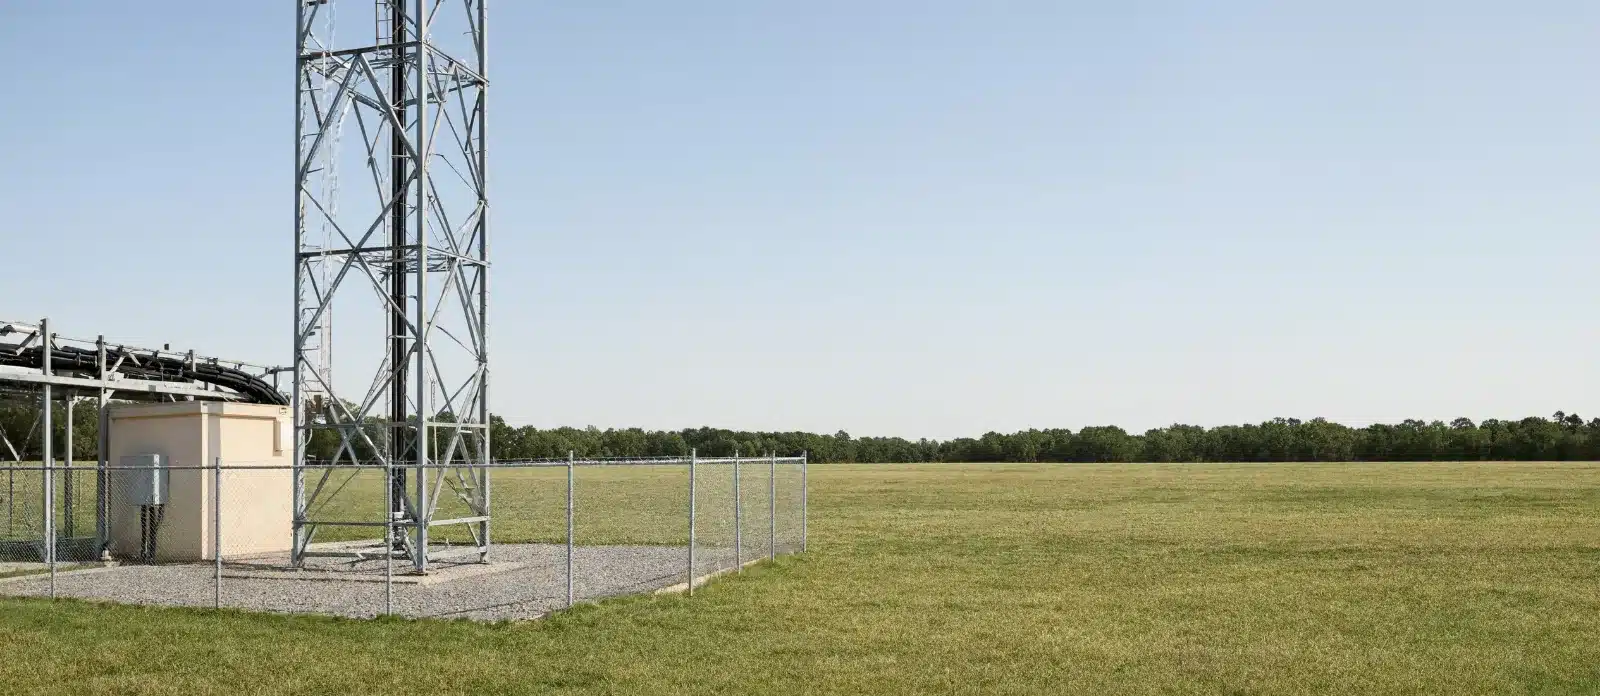
A quarter acre under a billboard, the fenced compound beneath a cell tower, a strip crossed by a transmission line or a rail spur: these parcels produce a small rent, generate a tax filing every year and almost never sell on their own. They are real property, and they can be donated. What matters is whether you own the ground, the easement, the income, or some combination.
Every property gets a look. Name, phone and email are the only required fields.
The first is the fee: you own a parcel, and somebody else holds an easement or a lease across it. Donating the parcel conveys the land together with the burden and the rent that comes with it. The second is the easement itself, held by the user rather than the landowner. The third is the income alone, the stream of lease payments without the land under it.
Those are not interchangeable, and the tax treatment is not the same. A gift of the underlying property is a real property gift. A gift carved out of an interest you keep runs into the partial interest rules in the Internal Revenue Code, which limit deductions for anything less than your entire interest or an undivided portion of it, with narrow exceptions such as qualified conservation contributions. We read the instrument first and tell you which category yours falls in.
If you own the dirt and somebody pays you to use part of it, you are almost certainly in the straightforward case.
The rent is real but small, and it arrives with an annual property tax bill, a schedule on a return and a lease that renews on the tenant’s terms rather than yours. Tower and billboard leases in particular are written with long option periods and escalators that favour the operator, and buyout offers from lease aggregators tend to arrive when the operator is about to renew.
For heirs the calculation is simpler. A remnant parcel with a tower on it is the last thing left in an estate, the one asset nobody wants to administer and no broker wants to list. A donation ends the filings and produces a deduction supported by an appraisal of the income the parcel actually earns.
These three make the valuation conversation short.
With the rent, the escalator, the renewal options and the current term end date.
Who pays, how much and how recently. A year of statements is plenty.
Including whether the parcel is severed from a larger tract or still part of one.
That is the case to be careful with. A gift of income alone, separated from the property that produces it, is not treated the same as a gift of the property, and the partial interest rules limit what can be deducted. Tell us what you want to keep and we will tell you what that does before you commit to it.
Frequently yes, with a survey and a new legal description. A carved-out parcel donated in full is a different thing from a carved-out right in property you retain, and the first is far more straightforward.
That is your call and worth running both ways. A sale produces cash and a taxable gain; a donation produces a deduction based on appraised value and no gain on appreciated long-term property. We will not tell you which is better for your situation, and anyone who does without seeing your numbers is guessing.
The entity conveys, under whatever its operating agreement requires. See property held in an LLC for how those transfers are put together.
Chiefly on the income the lease produces and the security of that income, cross-checked against sales of comparable leased parcels. This is specialist work and the appraiser has to be one. Above $5,000 the IRS wants a qualified appraisal and Form 8283 Section B, commissioned and paid for by you.
We do not provide tax or legal advice. See IRS Publication 526, Publication 561 and the Form 8283 instructions, and consult your own advisor.
The county, the parcel number and the tenant name are enough to start.