
Step one
Tell us about the site
Address, building size, past and current uses, and anything owed against it. Send any environmental report, survey or lease you have. A specialist reviews it and calls back.
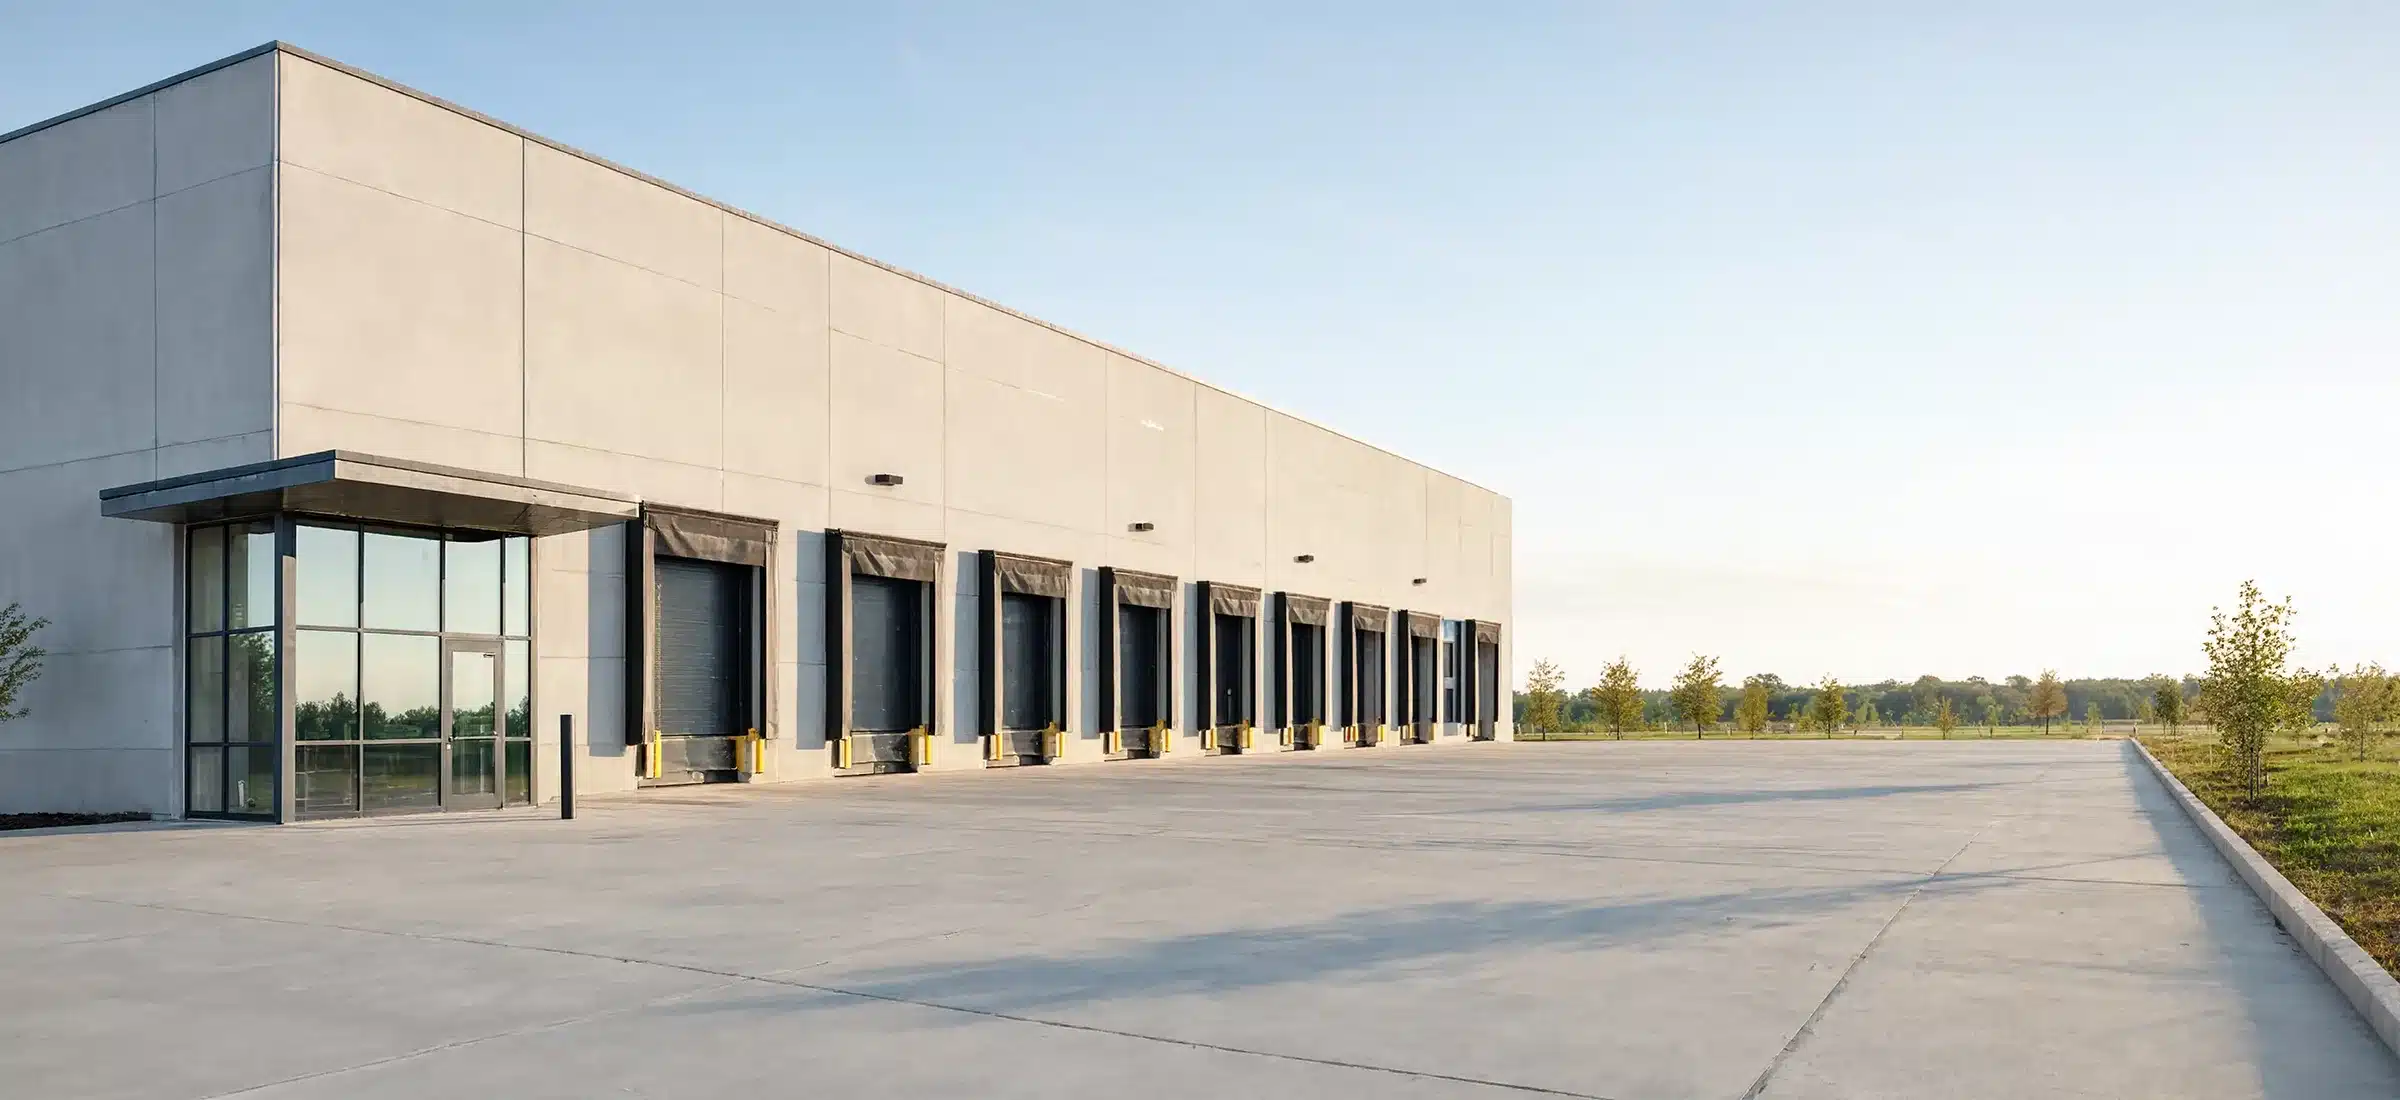
Real Estate with Causes accepts donated industrial real estate nationwide: warehouses and distribution buildings, light manufacturing plants, flex space, contractor yards, rail-served sites and self-storage. Industrial buildings are one of the property types where the numbers most often support us taking on costs a smaller property could not carry, including cleanout of equipment left behind. We prepare and record the deed ourselves.
Every property gets a look. Name, phone and email are the only required fields.
Industrial gifts get an environmental look that houses and vacant lots usually do not. That is the one extra step, and we tell you early what it involves for your site.
Address, building size, past and current uses, and anything owed against it. Send any environmental report, survey or lease you have. A specialist reviews it and calls back.
Your advisor and ours confirm how the gift is structured, including any tenant or lender. Our staff prepares the deed for the state and records it with the county.
Taxes, insurance, maintenance, security and liability transfer on the day the deed records. You receive a written acknowledgment and, where required, a signed Form 8283.
Specialized industrial buildings can take a long time to sell, and buyers price every uncertainty. This is how the two routes compare.
| Selling the building | Donating the building | |
|---|---|---|
| Time to be done with it | Broker marketing to a narrow pool of buyers, lender-required environmental work and long due-diligence periods. | No marketing period and no buyer financing. The schedule is set by title, any tenant and the environmental review. |
| What you pay | Broker commission, seller closing costs, transfer tax where it applies, and carrying cost until closing. | No escrow, no closing and no commission. The qualified appraisal is your expense and your choice of appraiser. On industrial buildings we more often absorb costs such as equipment removal or back taxes where the value supports it. |
| Equipment left inside | Usually the seller’s problem to remove before closing, at the seller’s cost. | Tell us what is there. Fixtures that convey with the building are part of the gift; loose equipment is discussed case by case. |
| Environmental questions | A buyer’s lender typically requires a Phase I report, and findings can reprice or end the deal. | Part of our review too. An existing report saves time, and we talk through what is needed before anyone spends money. |
| Tax outcome | Capital gains on the appreciation, plus recapture of depreciation taken on the building. | A charitable deduction reported on Form 8283, generally based on fair market value for property held more than a year, subject to the depreciation rules and the 30% of AGI limit. |
| Where the value goes | To you, less commission, closing costs and tax. | To our charitable programs, less the cost of the transfer and the sale. |
We do not provide tax or legal advice. Deduction outcomes depend on holding period, property type, use and a qualified appraisal. See IRS Publication 526, Publication 561 and the Form 8283 instructions, and consult your own advisor.
Six kinds of industrial property that reach us. Find the one closest to yours, or call and describe it.
 Older brick warehouses
Multi-story masonry buildings from the early 1900s, often in districts now being converted. Structure, roof and floor loads matter more than finishes.
 Flex and service-bay buildings
Office up front, roll-up doors behind. Often held in an LLC with several small tenants, which the gift can carry over intact.
 Self-storage facilities
Occupied units, rental agreements and a management contract all transfer. We look at occupancy and the condition of doors and roofs.
 Former manufacturing plants
The business moved or closed and the building is empty. Past processes decide what the environmental review needs to look at.
 Contractor yards and shops
Fenced yards with a shop building, often on the edge of town. Fuel storage and vehicle maintenance history are the first questions.
 Rail-served sites
Buildings with a spur or siding. Track agreements with the railroad are part of the transfer and we review them with the deed.
Industrial property carries the same core rules as any appreciated real estate, with depreciation and entity ownership coming up more often.
For property held more than a year, the deduction is generally fair market value as established by a qualified appraisal, limited to 30% of adjusted gross income, with a five-year carryforward. Depreciation taken on the building can reduce the amount, so your advisor will need the schedule.
Above $5,000 the IRS requires a qualified appraisal and Form 8283 Section B, signed by the appraiser and acknowledged by us. Above $500,000 the appraisal is attached to your return. Industrial appraisals lean on income and comparable sales.
A building with a mortgage becomes a bargain sale, with gain to you on the debt portion. Property held in an LLC or corporation is donated by the entity, which has its own reporting. Bring your advisor in early on both.
Tell us about it and we will review it. What matters is what the issue is, whether it has been investigated or cleaned up, and what a buyer would need to see. Some sites work as donations and some are better handled another way, and we will say which on the phone rather than after you have spent money on reports.
Not necessarily. Fixtures that are part of the building, such as crane rails, dock levelers and built-in systems, normally convey with it. Loose machinery and inventory are discussed case by case, and on industrial buildings we sometimes take on the removal ourselves where the value supports it.
For most industrial property it is part of our review. If you already have one, even a few years old, send it. If you do not, we will talk through whether one is needed and what scope makes sense before anyone commissions it.
It is possible, but a leaseback has to be at fair market rent and properly documented, or it can undermine the deduction. Your advisor should be involved, and we will look at whether a leaseback fits how we plan to hold or sell the property.
You do not recognize gain on a gift the way you would on a sale, but depreciation you have taken can reduce the deduction itself, depending on the type of property and the depreciation method. This is a question for your tax advisor with your depreciation schedule in hand.
Eight other property classes, each with its own transfer rules and its own page.
Send the address, what the building was used for and what is still inside, and we will tell you plainly what a donation would involve.