
A rent roll
Lots, occupancy, lot rents and any park-owned homes.
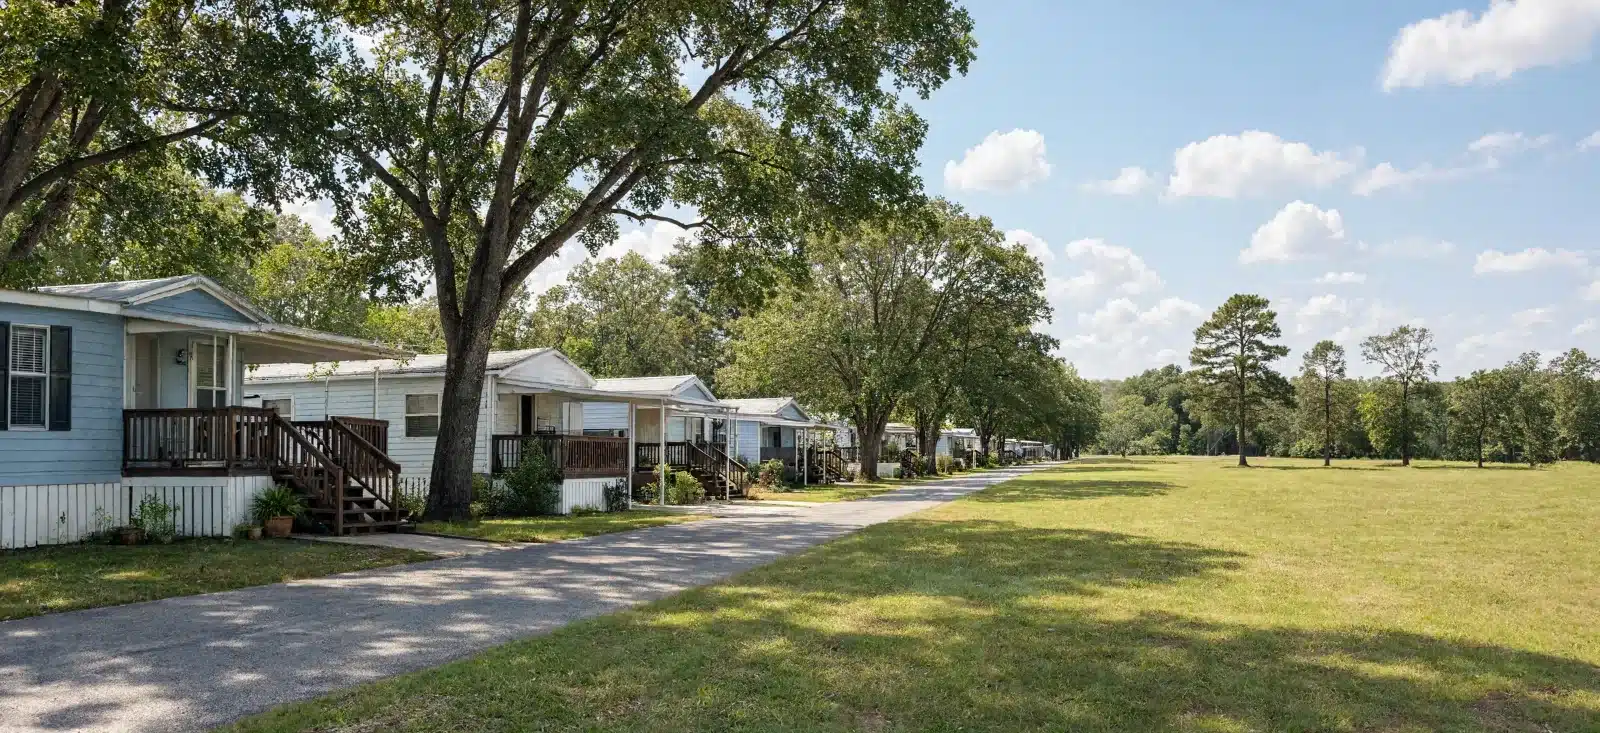
A manufactured housing community is land, infrastructure and dozens of resident relationships all at once: lot rents, water and sewer systems, park-owned homes and state rules that protect residents. Real Estate with Causes reviews donated mobile home parks and manufactured housing communities nationwide. Resident leases transfer with the park, and we take over as owner from the recording date.
Every property gets a look. Name, phone and email are the only required fields.
Whether the park is on city water and sewer or runs its own well and septic or package plant is one of the biggest factors in its value. Private systems carry permits, testing and replacement costs that a buyer prices carefully.
Homes the park owns and rents out are personal property, separate from the land, and are handled separately in the gift.
Many states give residents notice rights, and some a right to purchase, when a park changes hands. We check what applies.
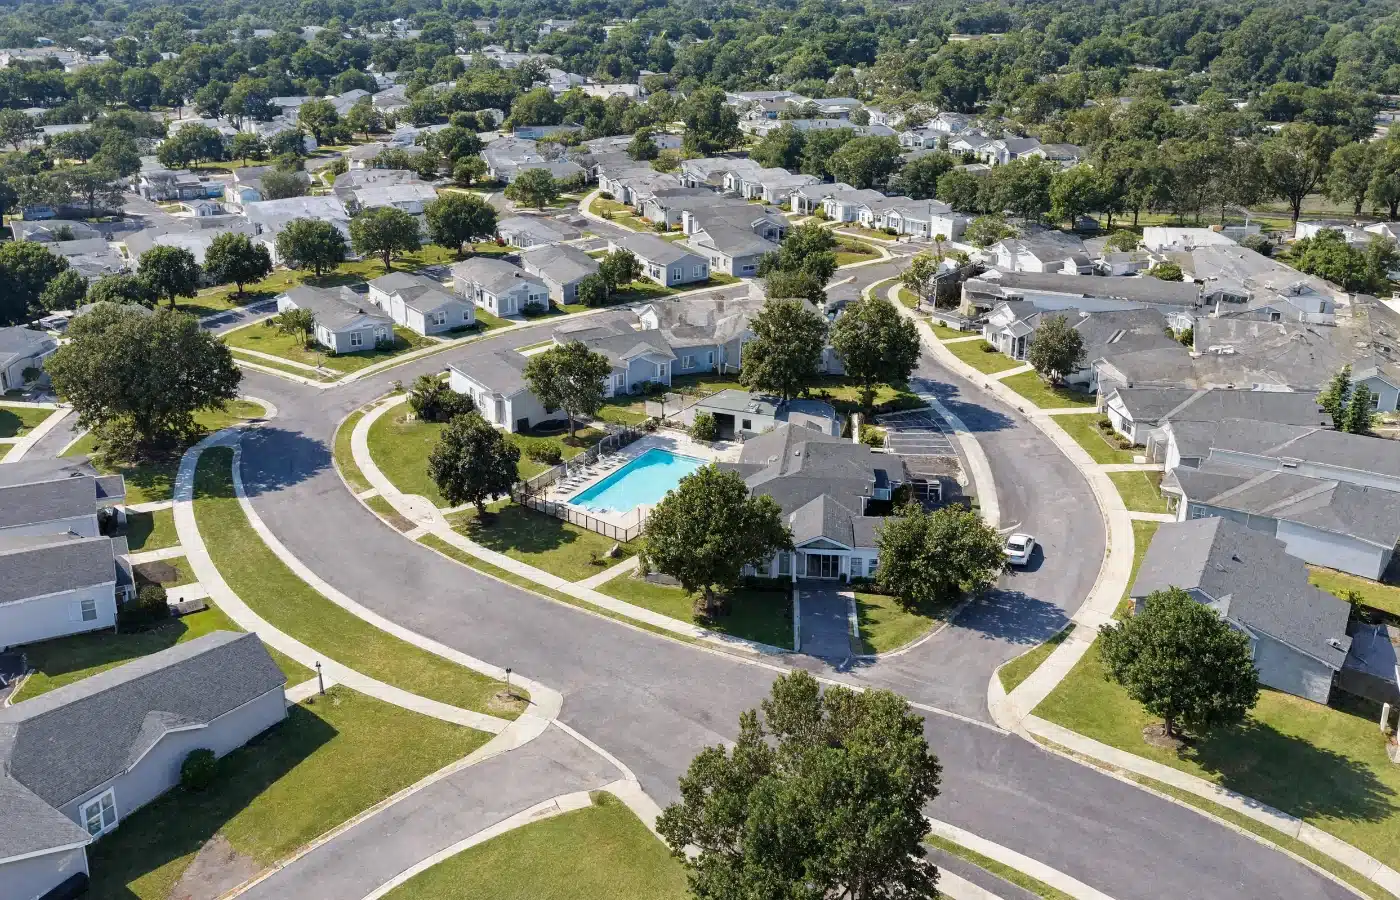
For a park held more than a year, the deduction is generally its appraised fair market value, limited to 30% of AGI with a five-year carryforward, and depreciation on infrastructure can reduce it.
Parks held in an LLC or partnership are donated by the entity. Your advisor will need the depreciation schedule and the entity’s tax treatment.
Park owners usually track all of this already.
Lots, occupancy, lot rents and any park-owned homes.
City or private water and sewer, and any permits or recent test results.
Income and expenses for the past year or two.
Yes. Leases stay in force with the new owner, and residents are notified under your state’s rules.
In some states they do, or they must receive notice before a transfer. We check your state’s requirements before the gift.
Park-owned homes are personal property and are appraised and transferred separately from the land.
It is a factor we review closely, along with permits and testing history. It affects value, not whether we look.
Yes, for review. RV parks are valued on their income and occupancy the same way.
We do not provide tax or legal advice. See IRS Publication 526, Publication 561 and the Form 8283 instructions, and consult your own advisor.
Send the address, the number of lots and the utilities, and we will tell you plainly what a donation would look like.