The deed and unit number
Plus the parcel number if the county assesses the unit separately.
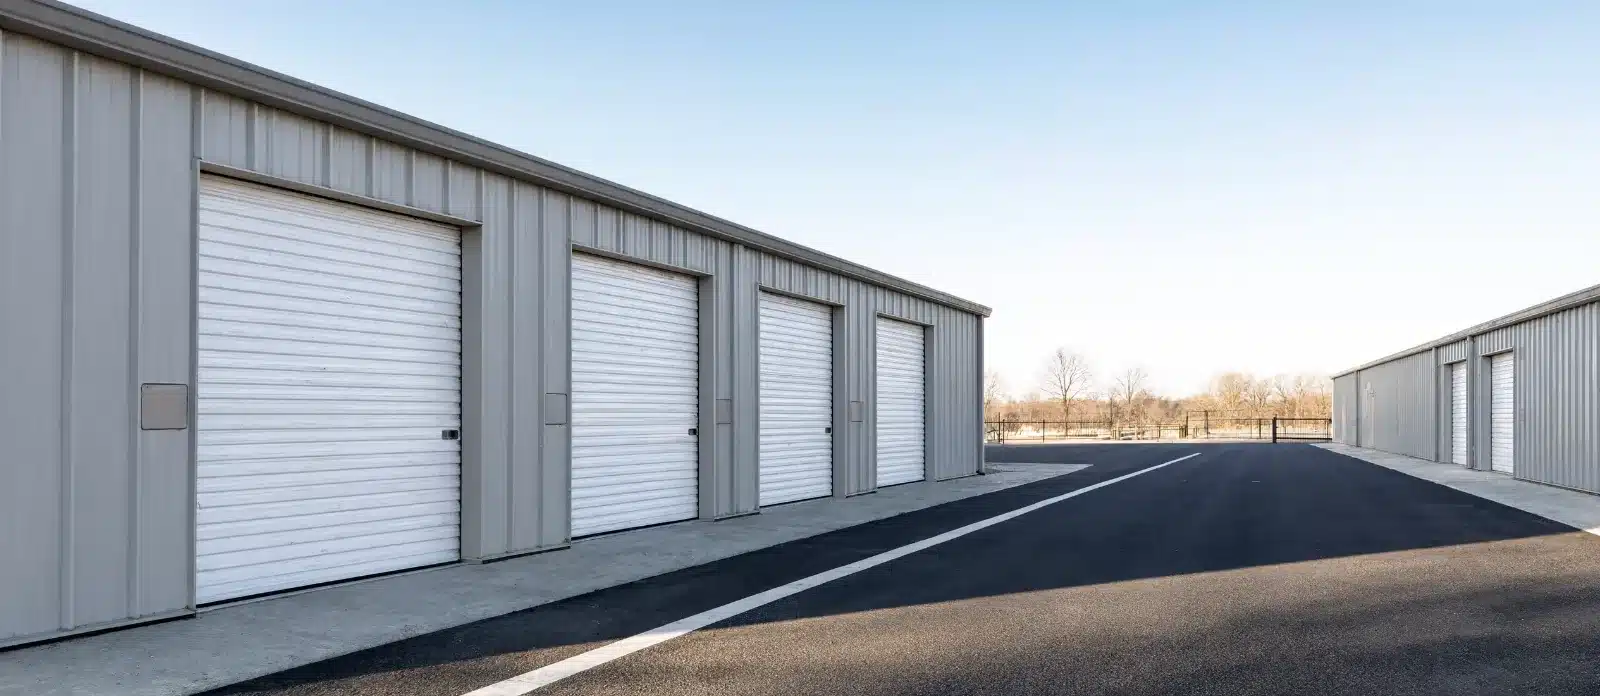
Deeded storage condos and deeded parking spaces are small pieces of real property that behave like large ones: a recorded deed, a unit number, a property tax bill and an owners association that bills monthly. When the boat, the classic car or the business inventory they were bought for is gone, the dues are not. Both can be donated.
Every property gets a look. Name, phone and email are the only required fields.
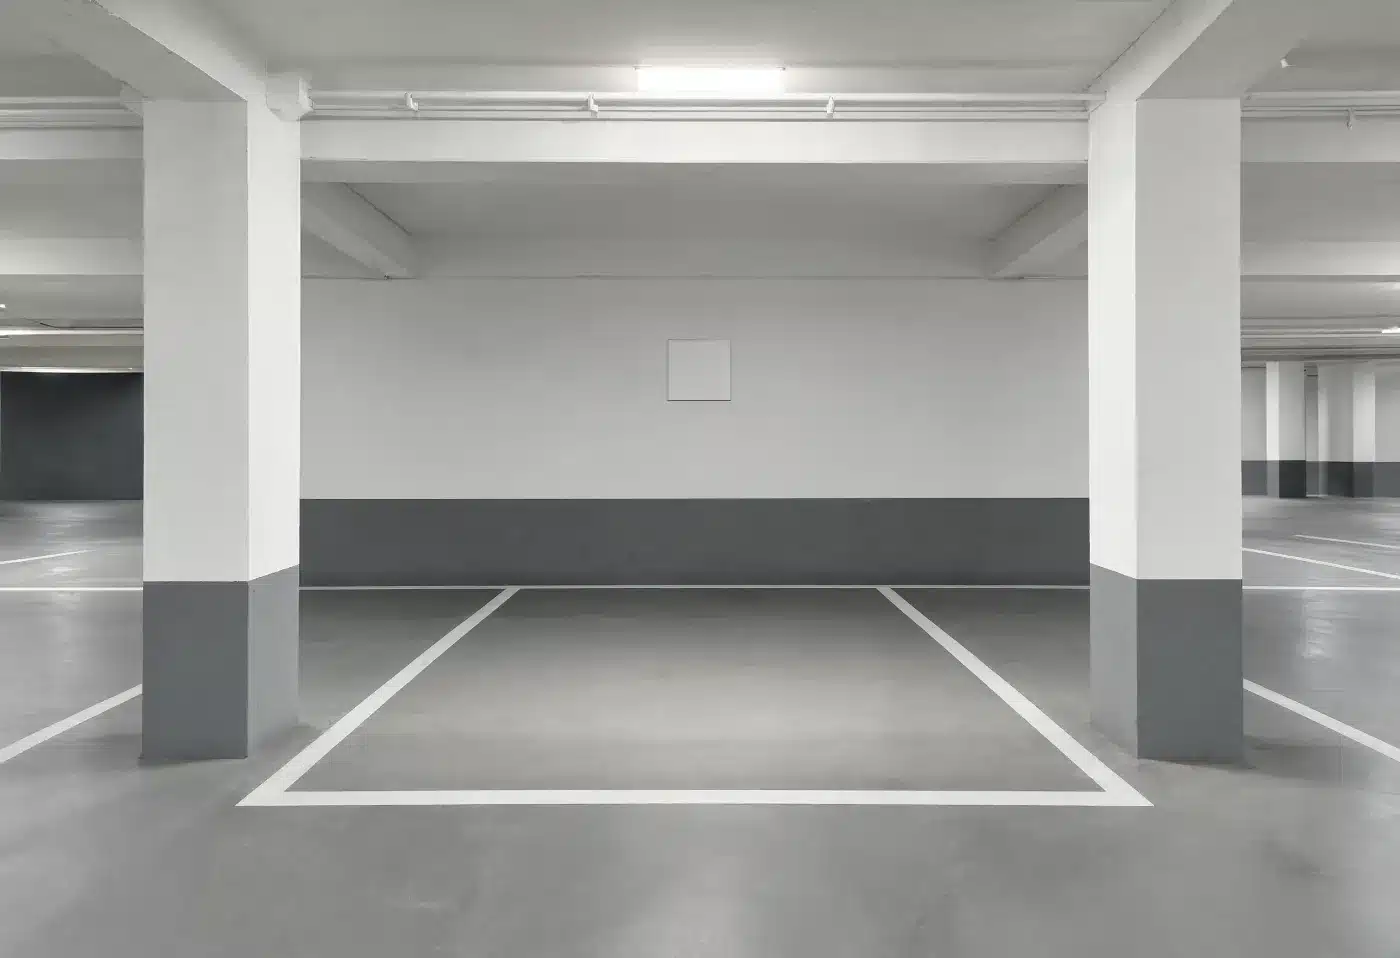
A storage condominium is a warehouse divided into individually deeded bays, typically with a roll-up door, power and a share of the common drive. Owners buy them for boats, RVs, collector cars, tools and business stock. A parking condominium is the same idea reduced to a painted rectangle in a garage, most often in dense city buildings where spaces are sold separately from apartments.
Both transfer by deed, both carry an association with a declaration and rules, and both can be given to a charity in the same way a condo apartment can. The wrinkle is usually in the declaration rather than the deed.
Some buildings restrict parking space ownership to residents of the building. Where that is the case, the space cannot simply be deeded to an outside owner, and the route becomes a sale to an eligible buyer with a cash gift of the proceeds.
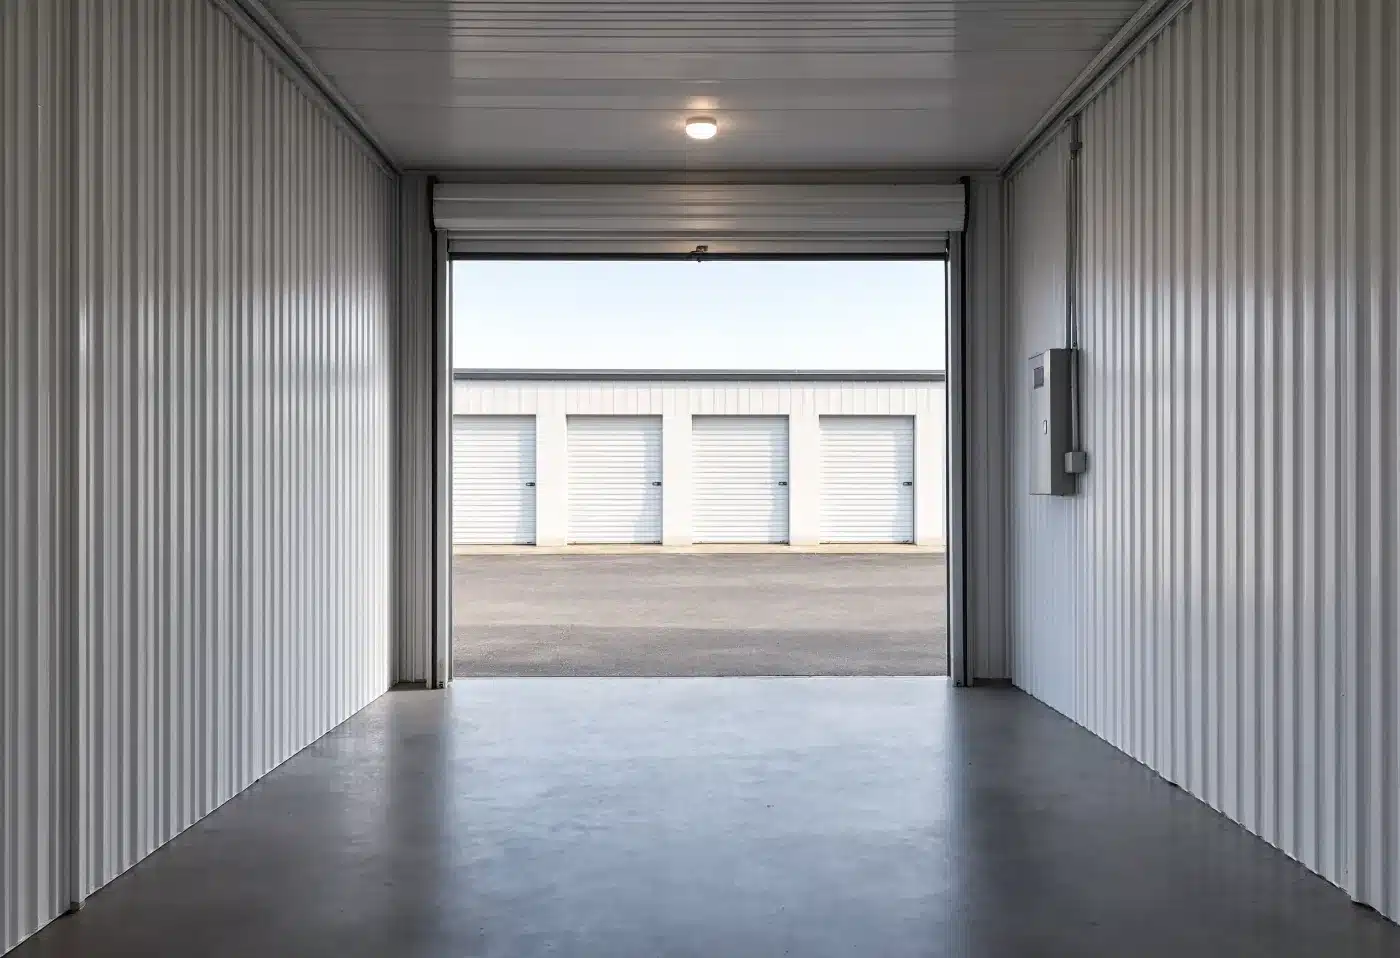
The monthly fee is the whole story. A storage bay that cost very little to buy can run for decades of dues, insurance and taxes on something now holding nothing but boxes. Owners who have downsized out of the hobby or closed the business usually want it finished rather than marketed.
City parking spaces have a narrower problem: the buyer pool is the building itself. If nobody in the building wants a second space this year, the space sits. A donation takes it off your ledger at appraised value rather than at whatever the one interested neighbour offers.
Three things and we can usually answer the same week.
Plus the parcel number if the county assesses the unit separately.
The monthly amount, the current balance and anything the association has voted for structural or door work.
Specifically whether an owner has to live in the building or belong to the association already.
We find out whether the board will make an exception, and if not we look at a sale to an eligible buyer with a cash gift of the proceeds, receipted in the ordinary way. It is a common outcome in city buildings and not a dead end.
Tell us what is in there. Cleanout is usually the donor’s responsibility, though on units where the numbers support it we absorb it. What we do not want is to discover the contents after the transfer.
Yes, and it is usually simpler. One appraisal covering multiple units and one transfer, with the deduction substantiated as a single gift of similar items on Form 8283.
No, that is a commercial property with tenants, income and different diligence. See self-storage facility donations for that.
From sales of comparable units in the same building or complex, which the association or the county records will show. Above $5,000 the IRS wants a qualified appraisal and Form 8283 Section B, commissioned and paid for by you.
We do not provide tax or legal advice. See IRS Publication 526, Publication 561 and the Form 8283 instructions, and consult your own advisor.
The building name and your unit number are enough to start.